 ?>
 By
Common Financial Errors UK Businesses Should Avoid
Good accounting is essential for every successful business. Whether you run a small startup, a growing SME, or an established company, accurate financial records help you understand your performance, manage cash flow, meet your tax obligations, and make better business decisions.
However, even seemingly small accounting mistakes can become expensive over time. Errors in bookkeeping, missed tax deadlines, poor record-keeping, and inadequate financial planning can result in unnecessary tax bills, penalties, cash flow problems, and lost business opportunities.
For UK business owners, maintaining accurate financial records is particularly important as HMRC continues to expand digital tax requirements and businesses face increasingly complex compliance obligations.
At TT Accountancy Services (TTAS), we help businesses across London and the UK maintain accurate accounts, manage their tax obligations, and make informed financial decisions. In this guide, we explore five common accounting mistakes that could cost your business thousands—and how to avoid them.
1. Mixing Personal and Business Finances
One of the most common mistakes made by small business owners is using the same bank account for personal and business transactions.
It may seem convenient, particularly when you’re starting out, but mixing finances makes it difficult to determine your company’s actual financial position.
Why It Can Be Costly
When personal and business transactions are mixed, you may:
- Lose track of legitimate business expenses
- Make bookkeeping more complicated
- Spend more time preparing accounts
- Struggle to calculate accurate profits
- Create problems when preparing tax returns
- Make financial reporting less reliable
How to Avoid It
Open a dedicated business bank account and use it exclusively for business transactions.
If you need to take money from the business for personal use, record it properly rather than simply transferring money without documentation.
Keeping finances separate creates a clearer picture of your business’s performance and makes accounting significantly easier.
2. Missing Tax and Filing Deadlines
Missing a tax deadline can turn a manageable financial obligation into an expensive problem.
Depending on your business structure and circumstances, you may have obligations relating to:
- Corporation Tax
- VAT
- PAYE
- Self Assessment
- Companies House filings
- Making Tax Digital requirements
Late filing and payment can result in penalties and interest.
Why It Can Be Costly
A missed deadline can lead to:
- Financial penalties
- Interest charges
- Additional administrative work
- HMRC correspondence
- Increased compliance risks
More importantly, repeatedly missing deadlines can create unnecessary stress and distract you from running your business.
How to Avoid It
Maintain a tax compliance calendar containing all relevant deadlines.
Don’t wait until the deadline approaches before preparing your records. Keep your bookkeeping up to date throughout the year and work with an accountant who can monitor your obligations.
3. Failing to Track Cash Flow
Profitability and cash flow are not the same thing.
A business can be profitable on paper and still struggle to pay its bills if customers take too long to pay or expenses become due before expected income arrives.
Why Cash Flow Matters
Poor cash flow management can result in:
- Difficulty paying suppliers
- Delayed salaries
- Increased borrowing
- Missed investment opportunities
- Difficulty meeting tax obligations
- Unnecessary financial pressure
How to Avoid It
Prepare a regular cash flow forecast that tracks:
Money coming in:
- Customer payments
- Sales revenue
- Investment
- Financing
Money going out:
- Salaries
- Rent
- Supplier payments
- Taxes
- Loan repayments
- Operating expenses
Review your cash flow regularly rather than waiting until your bank balance becomes a problem.
4. Failing to Keep Accurate Financial Records
Poor record-keeping can affect almost every aspect of your business finances.
Some businesses wait until the end of the financial year before organising receipts, invoices, bank transactions, and expenses.
This approach increases the risk of missing information and making mistakes.
Why It Can Be Costly
Inadequate records can result in:
- Incorrect tax calculations
- Missed allowable expenses
- Inaccurate financial statements
- Difficulties responding to HMRC enquiries
- Poor business decisions
- Additional accounting costs
How to Avoid It
Keep your records organised throughout the year.
Your records may include:
- Sales invoices
- Purchase invoices
- Receipts
- Bank statements
- Payroll records
- VAT records
- Expense records
- Loan documents
- Asset purchase information
Cloud accounting software can make this process considerably easier by helping businesses record and organise transactions digitally.
5. Trying to Handle Everything Without Professional Advice
Many business owners attempt to manage their bookkeeping, payroll, VAT, tax returns, financial reporting, and business planning themselves.
While some tasks can be managed internally, complicated accounting and tax matters can quickly become overwhelming.
Why It Can Be Costly
Without professional guidance, you could:
- Miss legitimate tax reliefs
- Misclassify expenses
- Submit incorrect tax returns
- Miss important deadlines
- Make poor financial decisions
- Spend valuable hours on administrative tasks
The cost isn’t always an obvious accounting error. Sometimes it’s the opportunity cost of spending your time on finances instead of growing your business.
How to Avoid It
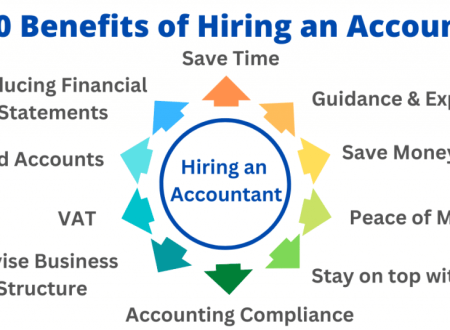
Consider working with an experienced accountant who can manage compliance while providing financial insight and strategic advice.
A good accountant should do more than prepare your year-end accounts. They should help you understand your numbers and identify opportunities to improve your business.
Bonus Mistake: Ignoring Your Financial Reports
Some business owners receive their accounts and immediately file them away without reviewing the information.
Your financial reports can tell you a great deal about the health of your business.
Regularly review:
- Revenue
- Gross profit
- Net profit
- Operating expenses
- Cash flow
- Debtor balances
- Creditor balances
- Tax liabilities
These figures can help you identify trends and make better decisions before small problems become expensive ones.
How to Prevent Costly Accounting Mistakes
A few simple habits can significantly improve your financial management.
Keep Your Books Updated
Don’t allow months of transactions to accumulate before recording them.
Reconcile Your Accounts Regularly
Compare your accounting records with your bank statements to identify missing or duplicate transactions.
Monitor Cash Flow
Know how much money is available today and what is expected to come in and go out in the coming weeks and months.
Plan for Tax
Set money aside for upcoming tax liabilities rather than treating tax payments as unexpected expenses.
Use Accounting Software
Digital accounting tools can simplify bookkeeping, invoicing, reporting, and bank reconciliation.
Review Your Numbers
Don’t simply record financial information—use it to make business decisions.
Get Professional Advice
An accountant can help identify risks and opportunities that may not be obvious to a business owner.
How TT Accountancy Services Can Help
At TT Accountancy Services, we help businesses across London and the UK avoid common accounting mistakes and build stronger financial systems.
Our services include:
- Bookkeeping and Bank Reconciliation
- Annual Accounts Preparation
- Corporation Tax Returns
- Self Assessment Tax Returns
- VAT Returns
- Payroll Services
- Management Accounts
- Cash Flow Forecasting
- Tax Planning
- Business Advisory Services
- Cloud Accounting Support
Whether you’re a sole trader, contractor, startup, landlord, or established SME, we can provide accounting support tailored to your business.
Accounting mistakes can be expensive, but many are completely avoidable.
Mixing personal and business finances, missing tax deadlines, ignoring cash flow, keeping poor records, and attempting complex accounting without professional support can all create unnecessary financial risks.
The good news is that you don’t have to manage everything alone.
By maintaining accurate records, monitoring your finances regularly, planning ahead, and working with experienced accounting professionals, you can reduce financial risks and focus more of your time on building a successful business.
Don’t Let Accounting Mistakes Cost Your Business Thousands
If you’re unsure whether your accounts are accurate or you’re concerned about your tax, bookkeeping, or cash flow, TT Accountancy Services can help.
Our team provides practical accounting and tax support to businesses across London and the UK, helping you stay compliant, understand your finances, and make better decisions.
Contact TTAS today to discuss your accounting needs and take control of your business finances.
Frequently Asked Questions
What is the most common accounting mistake small businesses make?
One of the most common mistakes is failing to maintain accurate and up-to-date financial records. Other frequent issues include mixing personal and business finances, missing tax deadlines, and failing to monitor cash flow.
Can accounting mistakes affect my tax bill?
Yes. Inaccurate records may cause a business to overpay or underpay tax. Failing to identify legitimate allowable expenses or tax reliefs can also result in paying more tax than necessary.
How often should a business update its accounting records?
Ideally, transactions should be recorded regularly throughout the year. The appropriate frequency depends on the size and transaction volume of the business, but monthly bookkeeping and bank reconciliation are good practices for many SMEs.
When should a small business hire an accountant?
A business may benefit from professional accounting support when its financial transactions become more complex, tax obligations increase, the business starts employing staff, or the owner wants more time to focus on growth and strategy.
Can an accountant help prevent HMRC penalties?
Yes. An accountant can help monitor relevant tax obligations, prepare returns, maintain accurate records, and remind you about applicable filing and payment deadlines. However, businesses remain responsible for meeting their legal obligations.